
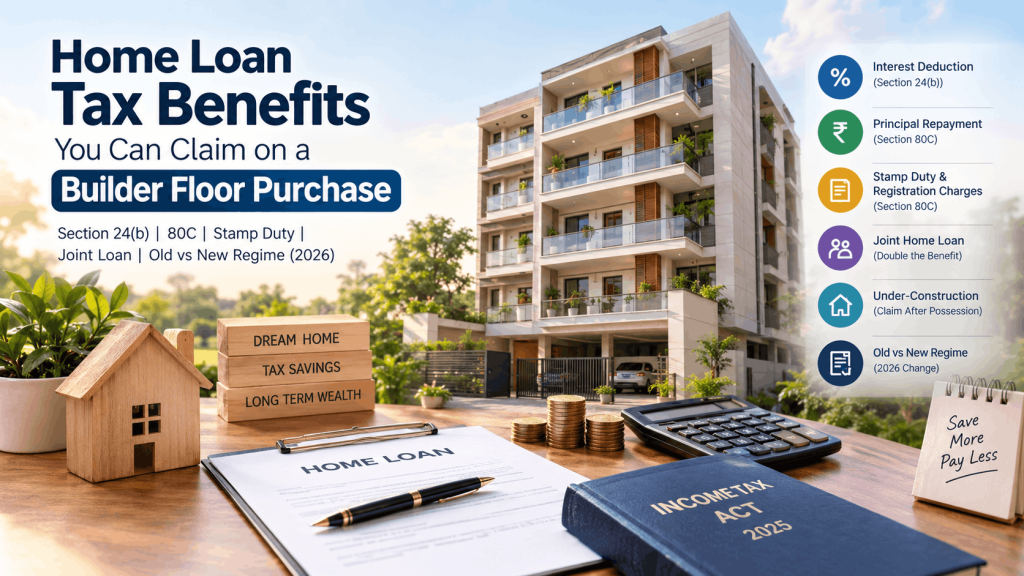
Buying a builder floor with a home loan does more than give you a home. It can also cut your tax bill every year. Most buyers only find this out after they’ve already signed the loan papers.
Let’s walk through what you can actually claim, and what changed in 2026.
Interest Deduction Under Section 24(b)
You pay interest on your home loan every month, and the tax law lets you deduct part of it. If you live in the floor yourself, you can claim up to ₹2 lakh per year as a deduction on the interest you pay.
This benefit works only under the old tax regime. If you choose the new regime, you lose this deduction on a self-occupied property. If you rent the floor out instead, the interest deduction works under both regimes.
Principal Repayment Under Section 80C
The part of your EMI that repays the loan itself also earns a deduction. Section 80C lets you claim up to ₹1.5 lakh per year on principal repayment.
Keep one thing in mind. The ₹1.5 lakh limit is shared with other investments like PPF, ELSS, and EPF. If those already fill your limit, your home loan principal adds nothing extra.
Stamp Duty and Registration Charges Also Count
Here’s a benefit most buyers miss. The stamp duty and registration fees you pay at the time of purchase also qualify for a deduction under Section 80C. You can claim them once, in the year you pay them, within the same ₹1.5 lakh cap.
On a ₹75 lakh builder floor, stamp duty alone can run into several lakhs. Claiming even part of that saves real money in your first year.
Joint Home Loans Double the Benefit
If you and your spouse buy together and both repay the loan, each of you can claim deductions separately. Each person can claim up to ₹2 lakh on interest and ₹1.5 lakh on principal. That brings the combined benefit to as much as ₹7 lakh per year.
Both of you must be co-owners and co-borrowers to claim this. Adding a name only for tax reasons doesn’t work.
What About Under-Construction Floors?
If you buy a floor that’s still under construction, you can’t claim interest deductions until you get possession. Once you receive possession, you can claim the interest you paid during construction. The tax law lets you spread that claim over five equal yearly installments.
That makes it worth keeping your loan interest statements from day one, even before the floor is ready.
The 2026 Change: New Income Tax Act
The Income Tax Act 2025 takes effect from 1 April 2026. It renumbers many sections. Principal repayment moves from Section 80C to Section 123, and interest moves from Section 24(b) to Section 22. The core benefits stay the same under the old regime.
The two older top-up deductions, Section 80EE and Section 80EEA, no longer apply to new loans. Their eligibility windows closed for loans sanctioned after March 2022.
Old Regime or New Regime?
The new regime offers lower slab rates but removes most home loan deductions for self-occupied homes. The old regime keeps the deductions but uses higher slab rates.
Neither one wins for everyone. If your home loan is large and you have other deductions, the old regime often saves more. If your loan is small, the new regime may come out ahead. Run both calculations before you file, or ask a chartered accountant to do it for you.
Final Thought
A builder floor loan works for you twice. It gives you a home, and it can lower your tax bill for years. Claim the interest, claim the principal, and don’t forget stamp duty in your first year. Check which regime saves you more, and keep every loan document safe. A quick conversation with a tax professional before you file can turn these deductions from theory into real savings.
This article shares general information and isn’t tax advice. Confirm your own eligibility with a qualified chartered accountant.
Talk to JMS Builder Floors
Thinking about buying a builder floor in Sector 95? Our team can walk you through pricing, approvals, and loan options. Visit the site, call us, or drop an email.
Address: Opposite Sare Homes, Sector 95, Gurugram, Haryana 122505
Email: nitin3875@gmail.com
Website: jmsbuilderfloors.com
“Tap the icon to call us now”
keywords: Section 24(b) home loan interest, Section 80C principal repayment, stamp duty tax deduction, joint home loan tax benefit, old vs new tax regime home loan, builder floor loan tax saving, Income Tax Act 2025 home loan